

Choose how much you can afford to spend before choosing a stake. Mathematics can describe the consequences of that choice; it cannot identify an amount that is safe for your household or require a larger deposit. Essential expenses, debt payments and money needed elsewhere are outside an entertainment allowance. Choosing not to wager is a valid budget decision, especially when the product’s minimum stake does not fit the amount you are willing to lose.
This guide uses fixed betting units and a declared finite-round model. Its tables replace unsupported session-risk estimates with a calculation you can reproduce. They do not report a live casino study, recommend 100 units as a universal minimum or promise long-term survival. A low probability of exhausting one particular modelled balance is not the same as a low expected spending cost or an affordable loss.
Define the unit before comparing balances
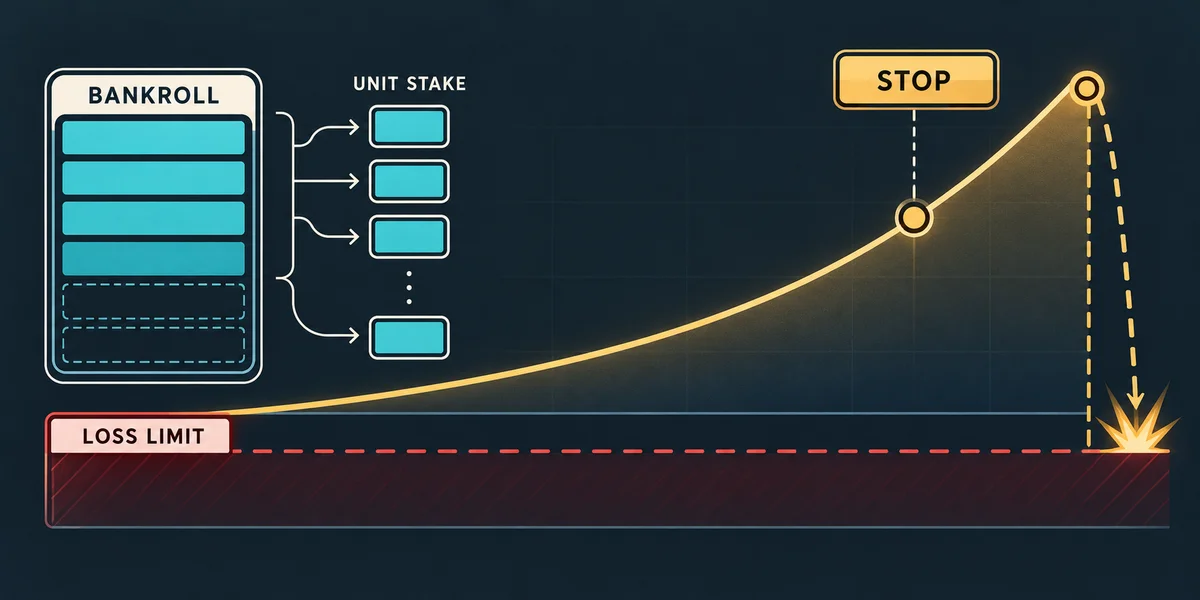
Let B be the chosen initial session allocation and S a fixed stake. The ratio U=B/S counts starting betting units. With B=100 and S=1 there are 100 units; with the same allocation and S=5 there are 20. This ratio is meaningful without choosing a currency. It says how many full stake losses the initial amount can cover, not how many rounds will occur or how long a session must last.
For a fixed one-unit stake, a 2x win earns one net unit and a loss costs one. At 1.5x a win earns half a unit. Gross return includes the stake: do not count the entire 1.5 as profit. Two simultaneous stakes must both be included in exposure, even if one is intended to cover the other after a successful cashout. A hoped-for payout cannot fund an order before it has settled.
A fixed stake equal to 1% of the initial allocation is not necessarily 1% later. After 100 falls to 50, the same stake 1 is 2% of the remaining balance. A current-balance fraction shrinks after losses and grows after wins. Rounding, minimum bets and replenishment can change it again. Do not mix those models in a table and call all of them the “one-percent rule.”
What the finite-risk tables count
Assume independent accepted wagers, fixed one-unit stakes, no fees, deposits or profit stops, and success probability 0.97/k at target k. Equality counts as a successful target. These are educational model assumptions, not measurements or confirmed protocol rules for every provider. We examine a maximum of 50,100 or 200 wagers rather than an unlimited future.
Failure means a settled balance below the next one-unit stake. It is absorbing: no borrowing or restarting after it occurs. A failure immediately after the last permitted round is included. At 1.5x a half-unit remainder cannot fund another unit, so the event is not necessarily a literal zero balance. This definition is different from losing 20% of the allocation, ending below the initial amount or experiencing a specified losing streak.
Target 2x: fixed-unit funding risk
| Initial fixed units | Failure by 50 | Failure by 100 | Failure by 200 |
|---|---|---|---|
| 10 | 21.387222% | 42.144905% | 62.507691% |
| 20 | 0.822430% | 8.110253% | 27.207995% |
| 50 | 3.893691e-13% | 0.000160% | 0.163216% |
| 100 | 0% | 1.516083e-27% | 1.025633e-09% |
For 100 units and 100 rounds, failure requires 100 losses with no wins. Its probability is 0.515^100, approximately 1.51608e-29, not 4.2%. A win would add a unit and prevent reaching zero within that horizon. With fewer than 100 rounds the event is impossible under those same rules. This strong horizon bound does not imply that a 100-unit allocation is safe to lose or that longer play has the same risk.
A 10-unit allocation, in contrast, has about 42.144905% probability of failure within 100 rounds in this model. The comparison changes the ratio of fixed stake to allocation. It does not instruct someone to increase their deposit: a smaller stake, shorter exposure, another affordable activity or no wager may better fit the spending boundary. If the required smaller stake is unavailable, adding money is not a mathematical necessity.
Target 1.5x: a different balance process
| Initial fixed units | Failure by 50 | Failure by 100 | Failure by 200 |
|---|---|---|---|
| 10 | 10.695767% | 29.913943% | 54.933938% |
| 20 | 0.048533% | 2.009122% | 14.831476% |
| 50 | 2.565846e-21% | 2.651233e-08% | 0.002315% |
| 100 | 0% | 6.583564e-44% | 3.867231e-17% |
At 1.5x the model succeeds with probability 97/150 and pays half a unit of net profit. Failure within 50 rounds from 100 units is impossible: even 50 losses leave 50 units. The table therefore shows exact zero for that event, not a rounded small positive probability. At 100 rounds,100 losses can exhaust the allocation, so the risk becomes positive, though extremely small under the assumptions.
The tables use ordinary percentages for moderate values and scientific notation for tiny ones. An entry such as 1.516083e-27% is a percentage; the corresponding probability is 100 times smaller. Tiny model numbers are sensitive to whether you kept the same horizon, stake and funding rule. They are not estimates of operator behaviour, access reliability or payment risk.
How to reproduce and check the calculation
Download finite_bankroll.py and runpython finite_bankroll.py. The script needs only Python’s standard library and makes no network calls. It prints the two reference tables. The callable function takes initial integer units, target 150 or 200 cents and a nonnegative horizon. Its optional exact mode uses rational probabilities for small examples.
The algorithm tracks probability mass at each funded balance. At each step it moves mass to the winning balance or the losing balance and accumulates any amount below one unit in an absorbing state. For 1.5x, balances are represented as integer half-units to avoid monetary-rounding ambiguity. For 2x the same representation gives equivalent whole-unit results. Active mass plus absorbed mass is checked throughout the final total.
Independent acceptance enumerated every win/loss path in 72 small configurations with exact fractions. For 2x, twelve larger cases were also checked against the closed-form first-passage sum for a biased unit random walk. The 100-loss identity and impossible 50-round case were verified separately. This is a reproducible mathematical reference, not an invented 100000-session experiment or a claim about median lifetime beyond the chosen horizon.
Set a spending boundary that can actually be followed
A loss limit is a personal restriction, not a return-improvement theorem. For example, starting at 100 with a chosen floor 80 and fixed stake 5, a balance of 82 cannot safely support another full stake while respecting that floor: a loss would leave 77. To preserve the boundary, stop before that wager. Quietly shrinking the stake would define a different strategy and needs to be recorded as such.
A profit boundary is also a stopping choice. A settled win may cross a target rather than land on it exactly. Checking the balance after settlement differs from guaranteeing an exact cashout or an immediate withdrawal. Pending wagers, simultaneous positions, fees and cashier restrictions can matter. Money removed from the session cannot be counted as still available to fund new wagers.
There is no universal percentage of disposable income or fixed session duration established by these formulas. Choose an amount and time boundary you can respect without replenishing losses. Do not label winnings “free money”: once paid, they are part of your resources. A pause or a stop can enforce the decision without claims about a guaranteed neurological reset or inevitable recovery.
Use the actual calculator capabilities
The Bankroll Calculator shows fixed-unit sizing, the declared model’s target chance, specified loss sequences, a turnover-cost reference and optional boundaries. It does not compute the complete session-failure distribution above. Its minimum illustrative stake is 0.10USD and the actual percentage is disclosed when that minimum exceeds the selected fraction. A calculator output does not override an affordable budget.
Under the declared negative-return model, constrained Kelly optimisation gives a zero stake. A positive recreational fraction is a spending choice, not a profitable Kelly recommendation. The expected-value guide explains why smaller units do not remove the expected cost of turnover. Direct partner actions remain registration choices without a compulsory demo stage; they are not a certificate that any session allocation is safe.