
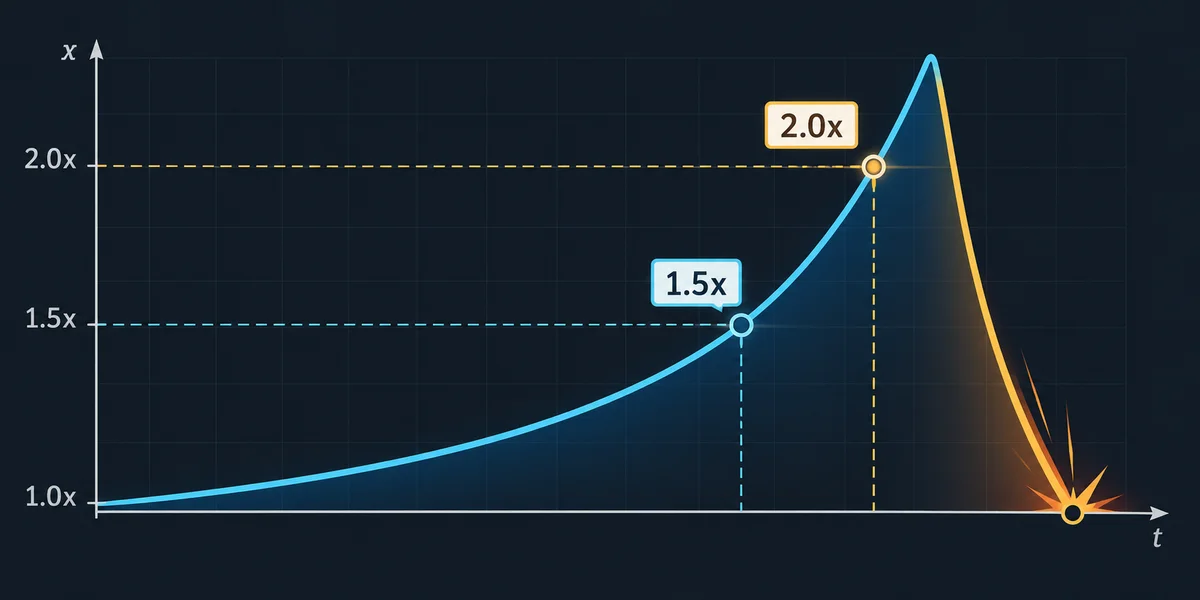


A 1.5x target succeeds more often than 2x in the model used here, but each winning stake earns less. Expected return, variance, loss sequences and a whole session’s funding risk answer different questions. The comparison is useful only when stakes, outcome law, settlement and stopping rules are explicit. A frequent win is not a guarantee of a profitable session or a reason to increase the amount you can afford to spend.
We assume independent accepted fixed targets with P(M≥k)=0.97/k, equality counted as success, no extra fees and a one-unit stake. This is a declared 3% reciprocal model, not a universal specification for every provider. Separate tables describe its analytical probabilities and one reproducible synthetic path. A calculated probability is not presented as a live casino measurement.
Compare like-for-like payments
At 1.5x the win probability is 97/150; at 2x it is 97/200. The difference is 16.166667 percentage points. Relative to the 2x probability,1.5x is one third higher, which is not the same as saying 16.17% higher. A successful 1.5x one-unit stake pays 1.5 gross and earns 0.5 net;2x pays 2 gross and earns 1 net. Net profit doubles, but gross payment increases by a factor 4/3.
| Metric, one-unit stake | Target 1.5x | Target 2x |
|---|---|---|
| Win probability | 64.666667% | 48.500000% |
| Loss probability | 35.333333% | 51.500000% |
| Gross on win | 1.500000 | 2.000000 |
| Net on win | 0.500000 | 1.000000 |
| Expected net | -0.030000 | -0.030000 |
| Variance | 0.514100 | 0.999100 |
| Standard deviation | 0.717008 | 0.999550 |
| Funding failure by 1000 | 0.182228% | 2.131958% |
Writing net result as k times the success indicator minus 1 gives expected net k×0.97/k-1=-0.03. Changing the target does not improve that expectation per accepted unit under these assumptions. It does change the distribution. The finite failure row uses 100 initial fixed betting units, at most 1000 rounds, no deposits or profit stop, and a settled balance below the next one-unit stake as absorption.
At 1.5x a half-unit remainder can trigger that funding event without literal zero. The probabilities are approximately 0.182228% and 2.131958% for this exact model. They are not recommended budget thresholds or universal provider failure rates. Different stake fractions, minimums, caps or stopping rules require a new calculation. A fixed initial 1% is also different from 1% of a changing balance.
Lower variance does not mean a smooth guaranteed path
For a one-unit binary result the variance is 0.97 k-0.9409:0.5141 at 1.5x and 0.9991 at 2x. Their ratio is 103/53≈1.943396, and standard deviations are approximately 0.717008 and 0.999550. These are properties of one accepted stake. They do not say that every lower-target path has shallow drawdowns, predictable losses or a particular emotional response.
Stake size is squared in variance. At the same current bank, staking 1.5% at 1.5x versus 0.75% at 2x gives variance ratio 4×0.5141/0.9991≈2.058252, not equality. Matching one-round variance would instead require a stake ratio about 1.394057. Even then, mean costs and the shape of increments differ; equal variance does not establish equal session failure probabilities. It is not a positive Kelly allocation rule.
Define the recovery path
After a one-unit deficit, a single funded 2x win adds 1 and restores it with probability 0.485. Two specified consecutive 1.5x wins add 0.5 each, with probability (97/150)^2 ≈ 0.418177778. These are defined short paths with different numbers of rounds. They are not a theorem that 2x is better for every recovery objective, bankroll or stopping horizon.
Additional losses increase the deficit. Over an unrestricted path, two wins need not be consecutive, but extra losing stakes mean more profit is required. A recovery probability must state when play stops, whether the next stake can be funded and which balance counts as restored. A high target paying more on a win also succeeds less often. Neither arithmetic creates an obligation to recover on the next round.
Windows, runs and session probability
With loss chance q, a specified block of j losses has probability q^j. In N rounds, the expected number of overlapping j-round all-loss windows is(N-j+1)q^j. The chance of at least one such run is different. A longer run contributes several windows and the indicators overlap. The table uses N=200 and calculates both quantities explicitly.
| Loss length in 200 | Expected windows 1.5x | P(at least once)1.5x | Expected windows 2x | P(at least once)2x |
|---|---|---|---|---|
| 3 | 8.734117 | 99.821094% | 27.044993 | 99.999999% |
| 5 | 1.079392 | 51.026183% | 7.100554 | 97.872017% |
| 7 | 0.133381 | 8.312154% | 1.864028 | 61.011490% |
For seven losses at 1.5x, the expected window count is about 0.133381 while the at-least-one probability is 8.312154%. It does not mean one occurrence in every eight sessions. At 2x, the expected count is 1.864028 but the event probability 61.011490%, not two occurrences guaranteed in every session. Expected counts can exceed 1; probabilities cannot. The exact run calculation was checked against an independent rational recurrence.
Two bets on one flight remain dependent
Consider two units accepted at 1.5x and one at 2x on the same flight, where the product supports those bets and targets. Total initial exposure is 3. If the 1.5x bet succeeds, its gross payment 3 covers that combined cost even if the second loses. That benefit is conditional on reaching 1.5x. Below it, both stakes lose together.
| Shared-flight outcome | Probability | Combined net on 3 units |
|---|---|---|
| M <1.5 | 35.333333% | -3.00 |
| 1.5 ≤ M <2 | 16.166667% | 0.00 |
| M ≥2 | 48.500000% | 2.00 |
The net outcomes are-3,0 and+2, with probabilities 53/150,97/600 and 97/200. Weighted expected net is-0.09 on 3 wagered units. The total variance is 5.1119 for that combined stake, including positive covariance. Treating the two legs as independent would give the wrong risk. The middle region is a conditional break-even outcome, not an unconditional shield or a guaranteed return of principal.
Replay both targets on the same file
The descriptive replay uses the first 1000 rows of the existing 10000-round synthetic CSV. It starts at 100 betting units and stakes one fixed unit on either target, with no fees or replenishment. The published helper stores 1000 account units and stakes 10; dividing money fields by 10 gives these betting units. The change of scale does not change wins, funding checks or drawdown percentages.
| Target | Wins /1000 | Turnover, betting units | Gross, betting units | Final, betting units | Maximum peak drawdown |
|---|---|---|---|---|---|
| 1.50x | 624 | 1000.00 | 936.00 | 36.00 | 66.341463% |
| 2.00x | 461 | 1000.00 | 922.00 | 22.00 | 78.846154% |
At 1.5x there are 624 wins,936 gross betting units paid and 36 left. At 2x there are 461 wins,922 gross and 22 left. Both paths fund all 1000 wagers. Peak-based maximum drawdowns are 66.341463% and 78.846154%, calculated over every settled point including the start and final state. These are single-path descriptive values, not median drawdowns from a simulated population.
Turnover is 1000 betting units in each replay. Final balance equals 100 initial plus gross minus turnover. Realised return is 93.6% or 92.2% on this finite file, not necessarily the model’s 97%. That variation does not establish a provider’s actual law. The file contains public synthetic inputs and cannot forecast an unrevealed private round. Sample accounting and population assumptions must remain separate.
Reproduce the probabilities and ledger
Save the full CSV, finite_bankroll.py and ev_ledgers.py beside the following Python example. It verifies the full file before selecting 1000 rows. The code uses standard libraries, no network and no real wagers. Four identical language blocks were executed and matched the displayed analytical values and replay summaries.
# Save finite_bankroll.py, ev_ledgers.py and the full synthetic CSV here.
from fractions import Fraction
from pathlib import Path
import json
import logging
from finite_bankroll import fixed_stake_failure
from ev_ledgers import load_rows, simulate

def run_probability(q, length, rounds):
    active = [Fraction(1)] + [Fraction(0)] * (length-1)
    absorbed = Fraction(0)
    for _ in range(rounds):
        following = [sum(active)*(1-q)] + [Fraction(0)]*(length-1)
        for j, mass in enumerate(active):
            if j+1 == length:
                absorbed += mass*q
            else:
                following[j+1] += mass*q
        active = following
    return float(absorbed)

rows = load_rows(Path("crashmath_10000_rounds_dataset.csv"))[:1000]
results = []
for cents in [150, 200]:
    k, p = Fraction(cents,100), Fraction(97,cents)
    mean = p*(k-1) - (1-p)
    variance = p*(k-1)**2 + (1-p) - mean**2
    sample, _ = simulate(rows, "target"+str(cents), cents, 1000)
    results.append({
        "target": float(k), "expectedNet": float(mean),
        "variance": float(variance),
        "failureBy1000": fixed_stake_failure(100, cents, 1000),
        "runs": [{"length": n, "atLeastOnce": run_probability(1-p,n,200),
                  "expectedWindows": float((201-n)*(1-p)**n)} for n in [3,5,7]],
        "sample": sample
    })
logging.basicConfig(level=logging.INFO, format="%(message)s")
logging.info(json.dumps(results, indent=2))
The finite failure calculation was independently checked with 60-digit Decimal states indexed by wins and round number. Its balance coordinate differs from the published half-unit balance DP. Run probabilities also matched exact rational recurrences. The 2000 replay rows were checked for accepted funding, Decimal target comparisons, gross payments, final balances, peaks and drawdowns. The references make the article reproducible without claiming a live study.
Keep execution and spending assumptions visible
The comparison assumes accepted fixed targets and their stated payments. A manual command accepted only at a higher arrival multiplier can follow a different payment contract. The execution comparison explains when fixed-target payment and arrival payment give different results. Neither the target table nor an auto setting guarantees zero latency, order acceptance or payout during every failure.
For these probabilities, unconstrained Kelly gives-0.06 at 1.5x and-0.03 at 2x; restricting stake fractions to nonnegative values selects zero for both. A positive entertainment fraction is a spending choice, not fractional Kelly generated from a profitable edge. There is no required 100-unit deposit or promise that lower variance makes an unaffordable loss acceptable.
The EV Calculator shows the selected model’s probability, expected return and related summaries. It does not produce a real hourly performance forecast from these targets. Partner actions remain direct registration choices without a compulsory demo. They do not certify a provider’s assumptions or guarantee a target’s availability. You can inspect all calculations before deciding whether to wager at all.