
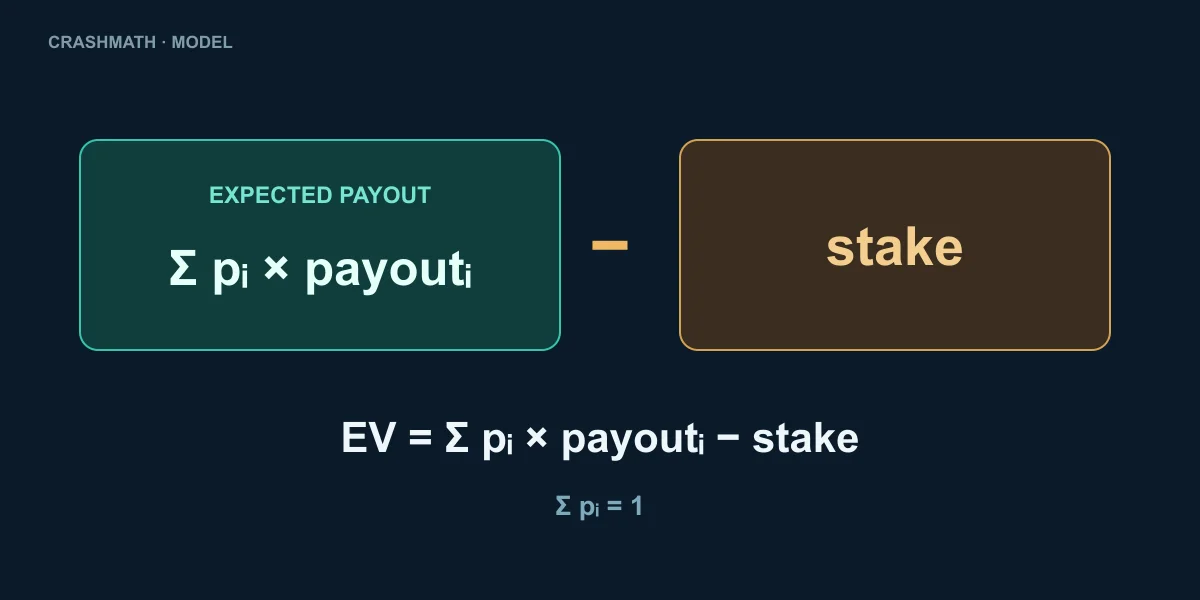


Expected value is the probability-weighted average of a defined payoff. You can calculate it for one wager; you do not need to play an infinite session first. In the reciprocal crash model used here, a fixed target above 1 has expected net result -E per unit staked, where E is the assumed house edge. That useful identity depends on the model and settlement rules. It is not a declaration that every named game has a 3% edge. This article keeps theory separate from three reproducible, funded examples on one public synthetic file.
1. Separate the stake, gross payout and net result
If you stake 10 units and an accepted wager pays at 2x, the gross payout is 20, including the stake, and net profit is 10. A losing wager returns zero and has net result -10. For a unit stake at target k, the two net outcomes are k-1 and -1. If p is the hit probability, EV=(k-1)p-(1-p)=kp-1. Confusing the gross payout with profit counts the original stake twice.
With E=0.03 and p=0.97/2=0.485, the 10-unit example has expectation 0.485*10-0.515*10=-0.30. The actual result of one wager is still either+10 or-10. Expectation is not a third possible settlement of-0.30, a prediction of the next balance or a charge that appears smoothly after every round. Keep the payoff definition consistent when comparing a formula with an account statement.
Over a ledger, starting balance plus gross payouts minus stakes must equal ending balance. Turnover is the sum of accepted stakes, including money reused after earlier wins. It is not necessarily the initial deposit or the peak balance. Realized RTP is gross payouts divided by turnover. Net profit is gross payouts minus turnover. These identities do not require a favourable probability model; they must reconcile for any recorded path.
2. Derive the fixed-target expectation
Assume independent model rounds with ideal survival probability p=(1-E)/k for supported targets k above 1. Suppose a successful accepted wager returns its stake times k and a failure returns nothing. Then EV=kp-1=k(1-E)/k-1=-E per unit. The target cancels algebraically. Under those assumptions, choosing a lower target raises the hit rate and reduces the size of a win, without changing the average edge.
| Target | Ideal hit probability | Expected net per unit | Unit standard deviation |
|---|---|---|---|
| 1.05x | 92.3810% | -0.03 | 0.278568 |
| 1.50x | 64.6667% | -0.03 | 0.717008 |
| 2.00x | 48.5000% | -0.03 | 0.999550 |
| 5.00x | 19.4000% | -0.03 | 1.977144 |
| 10.00x | 9.7000% | -0.03 | 2.959578 |
The standard deviation column describes one unit wager under this model, using variance k(1-E)-(1-E)^2. It does not measure an actual player population. A maximum payout, unsupported target precision, fees, changed rules or execution conditions can change the payoff calculation. The chosen edge must come from the relevant specification or be clearly labelled hypothetical. Do not infer a real game's return from the fact that a calculator accepts 3% as input.
Changing stake size based only on previous independent results does not create information about the next outcome. For a finite funded horizon with the same conditional edge, expected total profit equals -E times expected total turnover. This statement uses expected turnover. Substituting the turnover observed on one stopped path does not make the resulting line its conditional expected ending balance. A ledger and an ensemble expectation answer different questions.
3. The multiplier distribution is not the wager payoff
In an ideal unrounded reference, take U uniform in[0,1) and clamp 0.97/(1-U) from below at 1. Above 1 its density is 0.97/x² and the continuous-model median is 1.94x. The unbounded theoretical mean multiplier diverges. This does not prevent calculating a finite expectation for a fixed-target wager, whose gross outcomes are only zero or k. A bettor does not receive every future multiplier.
A finite sample of finite numbers always has a finite sample mean, even when the ideal population mean is infinite. Its existence therefore does not prove an operator enforces a cap. A finite 52-bit digest grid is itself bounded, and an actual product may impose further limits. A reported sample mean can be a valid description of that file; it is simply a different statistic from RTP for a specified betting rule.
After the reference multiplier is floored to cents and clamped at 1x, displayed 1.00x includes U<4/101, approximately 3.9604% in the continuous approximation. It is not just the 3% edge parameter. The model derivation explains the finite-grid count. Do not use a continuous density as though it described the rounded boundary atom, or assign settlement at exactly 1x without the game's rule.
4. Low targets change the shape of wins and losses
At 1.05x, one successful unit stake earns 0.05 net. Twenty such wins offset one full-unit loss before costs; those wins need not be consecutive for that accounting identity. The model hit probability is 97/105, about 92.3810%. The probability of a particular block of twenty independent wins is(97/105)^20≈20.4950%. The complementary event, at least one loss in that block, has probability 79.5050%.
Neither event is the probability of exhausting a bankroll. One loss can reduce a balance without emptying it. A run appearing somewhere within a longer sequence is also a different event from one prespecified block. Calling every loss a catastrophic wipeout replaces accounting with rhetoric. Keep the stake, starting balance, horizon and stopping rule visible before discussing depletion or survival.
5. Fractional Kelly does not turn zero into a positive stake
Kelly's original paper studies capital growth through betting allocation. For the two-outcome wager here, the log-growth optimum before a no-short constraint is f=(bp-q)/b, with b=k-1 and q=1-p. Substituting the declared crash probabilities gives f=-E/(k-1). It is negative when E is positive.
If the available choices are no wager or a nonnegative fraction on that wager, the constrained optimum is zero. Half of zero and a quarter of zero remain zero. A positive recreational stake of 1% or 0.2% is a chosen spending convention, not half-Kelly, quarter-Kelly or evidence of an optimal survival policy. Taking the opposite side is not assumed to be an available product.
A platform minimum can also exceed a chosen fraction as the balance falls. That changes the actual percentage staked. Rounding, minimums and funding must be specified in a simulation; otherwise a supposedly shrinking stake may quietly become impossible or exceed the available balance. A stop rule limits a session's exposure but does not reverse its assumed per-wager edge.
6. Reproduce three funded ledgers
Download the existing synthetic 10,000-round CSV and ev_ledgers.py. The script checks the exact file checksum and uses integer cents. All examples begin with 1,000 units. A stakes 10 at 1.10x; B stakes 5 at 2x; C stakes 0.2% of its current balance at 5x, floored to cents with a 0.10-unit minimum. C is discretionary sizing, not Kelly.
Before each wager the script checks funding. It stops if the next required amount is unavailable. It includes every completed round's balance when calculating drawdown, including the final point. The default output is the summary; an optional ledger file exposes each accepted stake and payout. These are retrospective illustrations on one synthetic path, not captured customer accounts or a controlled comparison changing only the cashout target.
python ev_ledgers.py crashmath_10000_rounds_dataset.csv
python ev_ledgers.py crashmath_10000_rounds_dataset.csv --ledger ledger.csv| Case | Completed wagers | Wins | Turnover | Gross payouts | Final balance |
|---|---|---|---|---|---|
| A | 2979 | 2618 | 29,790.00 | 28,798.00 | 8.00 |
| B | 2496 | 1148 | 12,480.00 | 11,480.00 | 0.00 |
| C | 10000 | 1932 | 12,757.89 | 12,227.25 | 469.36 |
All amounts are abstract accounting units, not verified operator deposit or stake limits. The 0.10 minimum belongs to this example. It does not state the minimum of a real game or recommend a funding amount. A reader reproducing another currency or precision must declare the new rounding rule and recalculate the complete ledger.
A ends with 8 units and cannot fund the next 10-unit wager. Its balance is not zero. B exhausts its balance and also stops early. C completes the file with 469.36 units. For C,12,227.25 of gross payouts minus 12,757.89 of turnover gives-530.64, reconciling the initial 1,000 with the ending 469.36. All win counts are integers and no unfunded wagers are added to force every example to 10,000.
7. Read drawdown and realized RTP from the same path
Drawdown at a point is the decline from the highest balance seen up to that point, divided by that peak. Maximum percentage drawdown is the largest such ratio over all completed points. It is not necessarily the initial-bank loss percentage or the difference between the overall peak and final balance. A later recovery does not erase an earlier deeper drawdown.
Keep the published round order. Reordering the same multipliers can change when funding runs out, the current-balance stakes and drawdown, even if the complete file frequencies stay the same. Record the starting balance and all rounding choices as part of a reproduction. An attractive result after changing the order is another experiment and cannot silently replace this ledger.
| Case | Peak balance | Maximum drawdown | Realized RTP | First unfunded round |
|---|---|---|---|---|
| A | 1,008.00 | 99.2063% | 96.6700% | 2980 |
| B | 1,020.00 | 100.0000% | 91.9872% | 2497 |
| C | 1,040.89 | 60.3493% | 95.8407% | File completed |
The realized RTPs differ materially from 97%. That does not turn the file into a production audit or establish the true parameters of a real game. The examples use different amounts, targets and stopping times. They cannot identify the target alone as the cause of a difference, and C's survival on this path does not estimate its population survival probability. The simulation terminal likewise labels a single path as a path outcome.
8. Include rewards and caps only under their actual rules
A hypothetical rebate of 15% of theoretical loss would change a 3% reference cost to 0.03*(1-0.15)=2.55%, before other conditions. That is different from returning 15% of turnover, paying 15% of cash losses or crediting a nonwithdrawable bonus. The actual base, eligibility, caps, expiry and cash value need the current terms. No universal 1win or other operator reward is assumed here.
Similarly, fully financed turnover of 35 times bonus amount B at a 3% model edge has expected wagering cost 1.05B. Whether a promotion has positive net value also depends on usable bonus value, contribution rates, restrictions and fees. The arithmetic alone does not establish that every promotion loses money or that an advantageous one would necessarily bankrupt an operator. A payout cap requires recalculating the actual payable amount, not automatically assigning a-100% expectation beyond it.
The EV calculator calculates results from entered assumptions; it does not read an account or verify bonus eligibility. Direct partner actions remain separate from the tools. The useful output is a stated model and a reconciled ledger, with unknown real-world conditions left explicit.